Licensed life insurance agent · Orlando, FL · 19 states
Protecting what you've built.
My job is to make sure you understand every option before you decide. You should never sign something you can't explain back to me. Angel Gonzalez Gines
- No cost, no obligation
- Appointed with multiple carriers
- (929) 696-2188
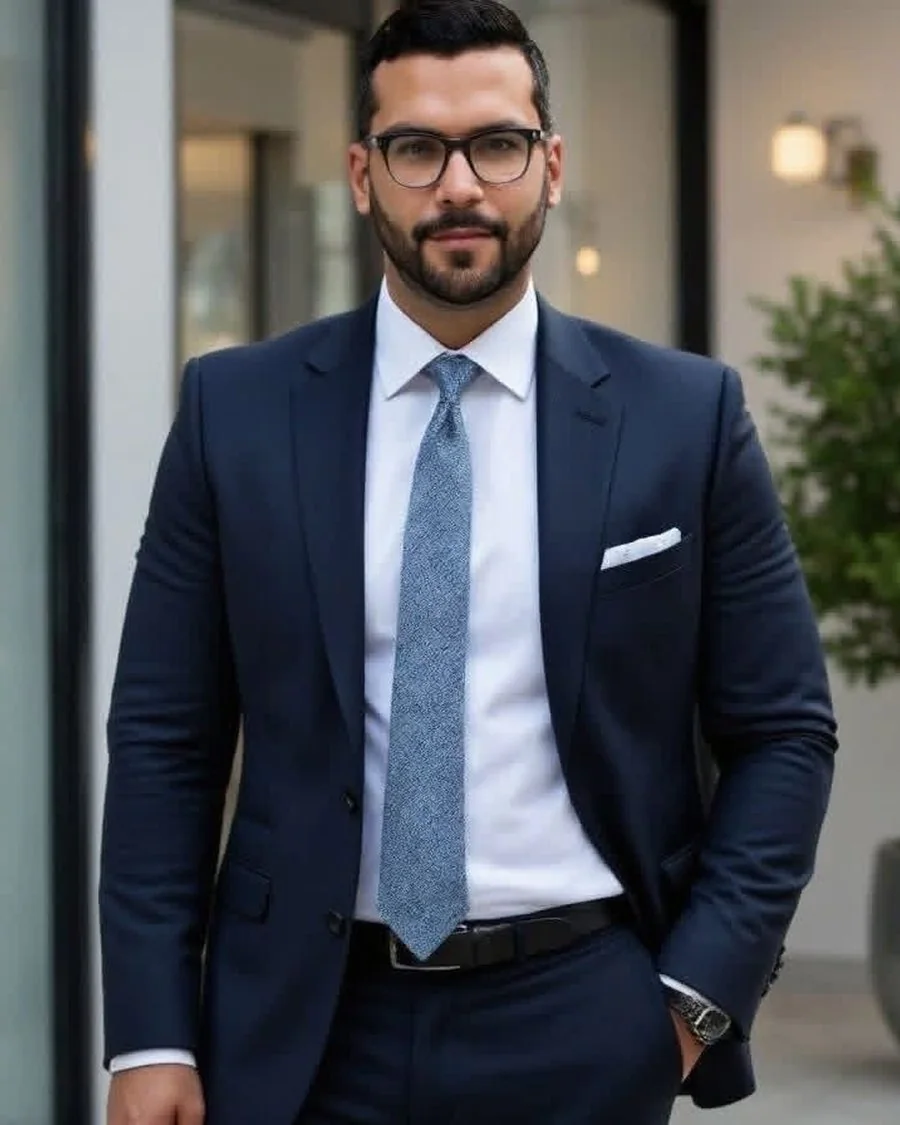
01 About Angel
A finance background, and a habit of translating it.
My background spans financial services, operations, and consulting. The thread running through all of it has been the same: taking something complicated and making it make sense to the person it actually affects.
As a licensed life insurance agent, I work with clients to identify the right coverage for their individual needs. Not the biggest policy, and not the one that pays me best. The one that fits the household in front of me.
Most people delay buying life insurance because they don't know where to start. The jargon is dense, the sales pitches are loud, and it's hard to tell who is actually on your side. So I start by explaining instead of selling. If the honest answer is that you don't need what I offer, that's the answer you'll get.
Because I hold appointments with more than one carrier, I can lay real options side by side, trade-offs included, and let you decide with a clear head.
-
Licensed producerNPN 21242424 · verifiable through NIPR
-
19 states, one standardSame process wherever you live
-
Conversation firstNo forms until you want them
02 Why it matters
Four reasons people finally get around to it
Most clients come to me because of one of these. See which sounds like your life right now.
-
Income replacement
If you're the household's primary earner, a policy makes sure your family's standard of living survives your absence. The mortgage still gets paid, the kids stay in the same school, and nobody has to make a permanent decision during the worst week of their life. That is usually the job of term life insurance.
-
Debt & final expenses
Mortgages, medical bills, and funeral costs don't disappear. A well-structured policy keeps the people you love from covering them out of savings, or out of a fundraiser. Smaller obligations are often handled with final expense coverage.
-
Business continuity
Business owners carry a kind of exposure employees never see. Key person coverage, buy-sell agreements, and executive benefits keep a company standing when one of the people holding it up isn't there anymore. Employers looking at the wider package should start with group benefits.
-
Legacy planning
For those thinking about what they leave behind, permanent life insurance can transfer wealth to heirs in a tax-advantaged way, and it does that outside of probate. That usually means whole life or indexed universal life.
03 Coverage explained
Eight products, no jargon
Each product below has its own link, so you can send one straight to a spouse or a business partner. Tap any card to open it. Each one covers what the product actually is, who it tends to fit, and what to watch out for. The trade-offs matter as much as the benefits.
Term Life Insurance
Simple protection for a set number of years
You pay a fixed premium for a set period, typically 10, 20, or 30 years. If you pass away during that term, your beneficiaries receive the death benefit, generally income-tax-free. It's usually the most coverage you can buy per dollar.
Often a fit if: you want to cover a specific stretch of life: the mortgage years, the kids-at-home years, the paying-off-debt years.
Worth knowing: when the term ends, so does the coverage, unless the policy is renewed or converted. Renewing later costs more because you're older.
Whole Life Insurance
Permanent coverage that builds cash value
Whole life provides permanent coverage that doesn't expire as long as premiums are paid. It also accumulates guaranteed cash value over time, which you may be able to borrow against or withdraw during your lifetime.
Often a fit if: you want lifelong certainty, a level premium that never rises, and a policy that quietly builds value alongside the protection.
Worth knowing: premiums are meaningfully higher than term for the same death benefit, and cash value builds slowly in the early years. Loans and withdrawals reduce the death benefit.
Indexed Universal Life (IUL)
Permanent, flexible, index-linked growth
A flexible permanent policy that ties cash value growth to the performance of a market index, without putting your money directly in the market. Most designs include a floor that limits losses in a down year and a cap that limits gains in a strong one.
Often a fit if: you want permanent coverage, growth potential, and the ability to adjust premiums as your income changes.
Worth knowing: returns are not guaranteed. Caps, participation rates, and internal policy charges all affect results, and an underfunded policy can lapse. Illustrations are projections, not promises.
Final Expense Insurance
Small policy for end-of-life costs
Small whole life policies designed to cover death-related costs: funeral expenses, outstanding medical bills, and other end-of-life obligations. Underwriting is usually simplified, and many policies require no medical exam.
Often a fit if: you're older, have health history that complicates other products, or simply want to make sure nobody is paying out of pocket for your funeral.
Worth knowing: face amounts are modest by design, and some policies have a graded benefit period in the first couple of years. Read the benefit schedule carefully.
Long-Term Care (LTC)
Help paying for extended care
LTC coverage helps pay for extended care services that health insurance and Medicare typically do not, including in-home care, assisted living, and nursing facility care. It's one of the largest uncovered risks in most retirement plans.
Often a fit if: you'd rather not have a long care event drain retirement savings, or ask an adult child to become a full-time caregiver.
Worth knowing: benefits begin only when specific triggers are met, and daily limits, elimination periods, and inflation options vary a lot between policies.
Disability Insurance
Protects the paycheck itself
Your ability to earn an income is your most valuable financial asset. Disability insurance replaces a portion of that income if an illness or injury keeps you from working. Households underestimate this risk more than almost any other.
Often a fit if: your household runs on your paycheck, you're self-employed, or your employer coverage would replace far less than you think.
Worth knowing: the definition of "disability," the elimination period before benefits start, and the benefit period all differ between policies, and they matter enormously at claim time.
Employee Group Benefits
For businesses of any size
Group benefits allow businesses of all sizes to offer competitive employee packages, including group life, disability, dental, and vision. Often the most cost-effective way to raise total compensation without raising salaries.
Often a fit if: you're an owner trying to attract and keep good people, or you've outgrown the "we don't offer benefits yet" stage.
Worth knowing: group coverage generally ends when employment does, and amounts are often lower than what an individual policy would provide. Many people need both.
Fixed Annuities
Predictable growth, optional income
A contract with an insurance company that provides a guaranteed interest rate over a set period, with the option to convert the accumulated value into a stream of income later on. Growth is generally tax-deferred until you withdraw.
Often a fit if: you want a predictable, low-volatility place for a portion of savings, or a future paycheck you can't outlive.
Worth knowing: surrender charges usually apply to early withdrawals, and guarantees are backed by the claims-paying ability of the issuing insurer, not by a government agency.
04 How it works
Four steps. No surprises.
You can stop after any one of them. Most people are surprised how much of this is just talking.
Free conversation
We talk about your household, your goals, and what you want protected. No forms. No pressure. Just listening.
Needs analysis
I run a structured analysis to identify the right coverage amount and product category for your situation, with the math shown rather than hidden.
Options review
I present options that actually fit, explaining the trade-offs in plain language so you can decide with confidence.
Application & support
I guide you through every step and remain your point of contact after placement. Not just during the sale.
05 Your information
What happens to what you tell me
Insurance conversations involve health and money. Here is how that information is handled.
-
Never sold, never rented
Your details are not shared with data brokers, lead resellers, or marketing lists. They go only where an application requires them.
-
No trackers on this site
This page loads no advertising pixels, no third-party analytics, and no external scripts or fonts. Nothing follows you after you leave.
-
The form doesn't store anything
Sending a message opens your own email app with the note pre-filled. Nothing is saved to this website, so you keep the record too.
-
Ask and it's gone
Health and financial details are requested only when an application actually needs them, and you can ask me to delete what you've shared at any time.
06 Transparency & licensing
Check my work
Every license below is public record. You should verify anyone who asks you about your money, including me.
- Producer
- Angel Gonzalez Gines
- NPN
- 21242424
- Home state
- Florida
- Based in
- Orlando, Florida
Look up NPN 21242424 at NIPR Florida DFS licensee search
This page was last reviewed on .
States licensed Home state
Important disclosures
This website is an advertisement for insurance products and services. Angel Gonzalez Gines is a licensed life insurance producer (NPN 21242424), licensed in 19 states: Alabama, California, Florida (home state), Georgia, Illinois, Kentucky, Louisiana, Maryland, Michigan, Missouri, Mississippi, North Carolina, New Jersey, Ohio, Pennsylvania, South Carolina, Tennessee, Texas, and Virginia. License information is available upon request and verifiable through the National Insurance Producer Registry (NIPR) and each state's Department of Insurance.
I am appointed with more than one insurance carrier. Recommendations are based on your individual needs, health profile, and financial goals, and are limited to the carriers and products for which I hold an active appointment. Product availability, features, riders, underwriting, and guarantees vary by carrier and by state, and not all products are available in every state.
I am licensed to discuss and sell insurance products only. I do not provide tax, legal, investment, or accounting advice, and nothing on this site should be relied on as such. Consult your own tax professional or attorney regarding your specific situation.
Insurance products are not deposits, not FDIC or NCUA insured, not guaranteed by any bank or credit union, and are not backed by any federal government agency. All guarantees are subject to the claims-paying ability of the issuing insurance company. Products with a cash value component involve risk and are subject to market and policy conditions. Policy loans and withdrawals reduce cash value and the death benefit and may have tax consequences. Values shown in any policy illustration are projections, not guarantees, and past performance does not guarantee future results.
No policy is in force until an application has been submitted, underwritten, approved, and issued by the carrier, and the required premium has been paid. This site is not an offer or solicitation in any jurisdiction where the producer is not licensed or where such activity would be unlawful.
07 Common questions
The things people ask first
Does the first conversation cost anything?
Am I going to get a wave of phone calls?
Do I need a medical exam?
How much coverage do I actually need?
I already have coverage through work. Is that enough?
How do I confirm you're licensed in my state?
What happens when my term life insurance ends?
Does my life insurance through work follow me if I change jobs?
Can I get life insurance if I have a health condition?
Do you work with clients in Spanish or Portuguese?
How are you paid?
Get started
Let's have a conversation.
Pick a time that works, or send a note and I'll come back to you, usually the same day. There's no script on my end and no obligation on yours.
- A real 20 to 30 minute conversation
- No application unless you want one
- Your information stays with me